New money covers less than two-fifths of realized cap growth
Bitcoin’s recent price advance is increasingly dependent on existing holders trading coins at higher prices rather than fresh capital entering the market, according to Glassnode analysis published Oct. 8.
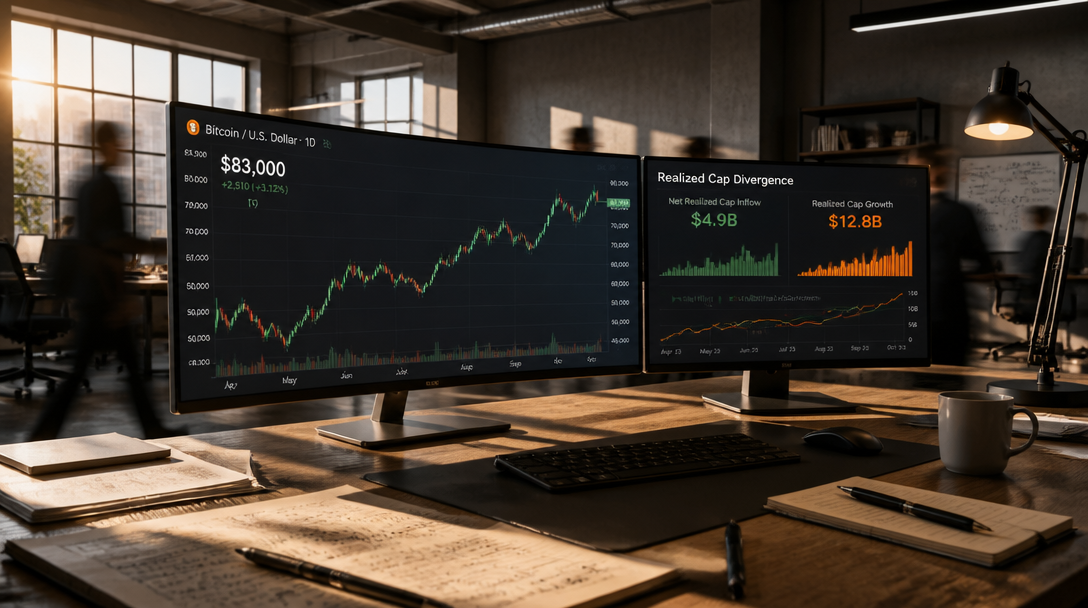
Rolling 30-day cumulative inflows of new money to Bitcoin totaled $4.9 billion as of Oct. 5, but those inflows accounted for less than two-fifths of the $12.8 billion growth in Bitcoin’s realized cap over the same period. Glassnode noted that “new money therefore covers less than two fifths of that rise. The rest is coins changing hands at higher prices among money already in the market.”
The distinction matters for price sustainability. Bitcoin attempted to rise beyond $87,000 four times since Sept. 21 but encountered thickening overhead ask liquidity on exchange order books. Short-term holders, defined as investors holding coins for fewer than 155 days, have become net sellers at higher prices.
On the day Bitcoin closed above $85,000, short-term holders sent 86% of all coins deposited to exchanges, the highest daily share in the past year. On a typical day, short-term holders account for under two-fifths of exchange deposits. Despite the profit-taking, short-term holders remain in net profit overall, with an aggregate realized price of $78,250 as of Oct. 7.
Glassnode highlighted a structural difference between the current rally and prior cycles. “The rallies of 2024 and 2025 showed a similar mix, but on far larger inflows. Until those inflows pick up, the move depends on existing holders paying more,” the firm stated.
Bitcoin traded at $83,000 at the time of writing, down 1% month-to-date. The realized cap metric values each coin at the price it last moved onchain, making it a measure of the average acquisition cost of the current holder base. US spot Bitcoin ETFs, which launched in January 2024, have historically been a significant source of institutional capital inflows.