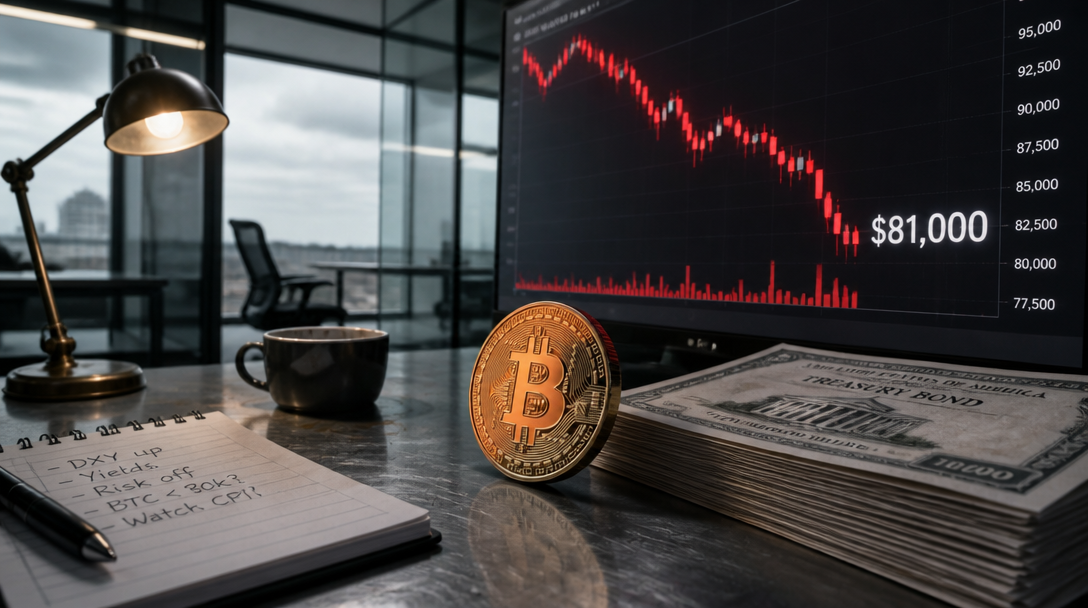
Bitcoin fell below $81,000 on October 22 as investors rushed into Treasury bonds while yields collapsed, dragging equities, gold, and silver lower in a synchronized market retreat.
The 10-year Treasury yield plummeted from 5.146% to below 5%, marking its sharpest single-day decline in more than two years. That rally in bond prices coincided with losses across traditional and crypto assets. The Nasdaq fell more than 2%. Spot gold dropped about 2.7% to $4,025. Silver sank about 5.8% to near $54.63. The dollar index slipped to its lowest level since October 1.
Bitcoin’s average acquisition cost via US spot Bitcoin ETFs stood near $81,500, according to Glassnode’s October 21 report on ETF flows. Replenished spot bids clustered near $80,000, while the True Market Mean settled near $77,600. Overhead supply runs from $85,000 to $87,500, leaving Bitcoin vulnerable to further downside if support breaks.
The selloff occurred while the Federal Reserve’s policy range sits at 3.75% to 4%. Markets price in roughly a 78% chance of a December rate hike. Treasury buyers may be weighing growth risk more heavily than inflation risk, the World Gold Council suggested in its October 19 Weekly Markets Monitor titled “Bonds back in the room.”
The Council raised the possibility that renewed safe-haven demand for bonds could compete with gold for capital. Gold’s two usual supports pointed higher despite the selloff, signaling an unusual market dynamic. Silver’s larger percentage drop reflects greater sensitivity to positioning and industrial demand.
Oil moved in the opposite direction. Brent crude hit an intraday high of $114.70, moving above $111 as renewed Houthi attacks in Saudi Arabia raised supply concerns. Dearer fuel feeds inflation and cuts household and corporate spending power.
Tech giants faced pressure alongside the broader market. Meta shares fell about 8% on October 22. The company reported third-quarter revenue of $64.6 billion, up 26%, but capital expenditures reached $34.9 billion and free cash flow was negative $2.1 billion. Meta raised the low end of its 2026 capex guidance by $5 billion to a range of $135 billion to $145 billion. Meta’s five-year credit default swap spread rose 7.6 basis points to a record 114.79.
Oracle’s credit default swap spread sat near a record. Amazon’s spread reached its highest level since March 2020. Both moves reflect heightened credit risk perception among investors.
Inflation expectations remained sticky. The preliminary Michigan survey put one-year inflation expectations at 4.7% and longer-term expectations at 3.5%. Consensus manufacturing PMI came in near 55.5 against 55.9 previously, while consensus services PMI stood near 58.0 against 58.8.
Bitcoin’s market cap stood at $1.64 trillion with 24-hour volume of $26.11 billion across a circulating supply of 20.1 million coins. The Fed is scheduled to announce its next policy decision on October 28.