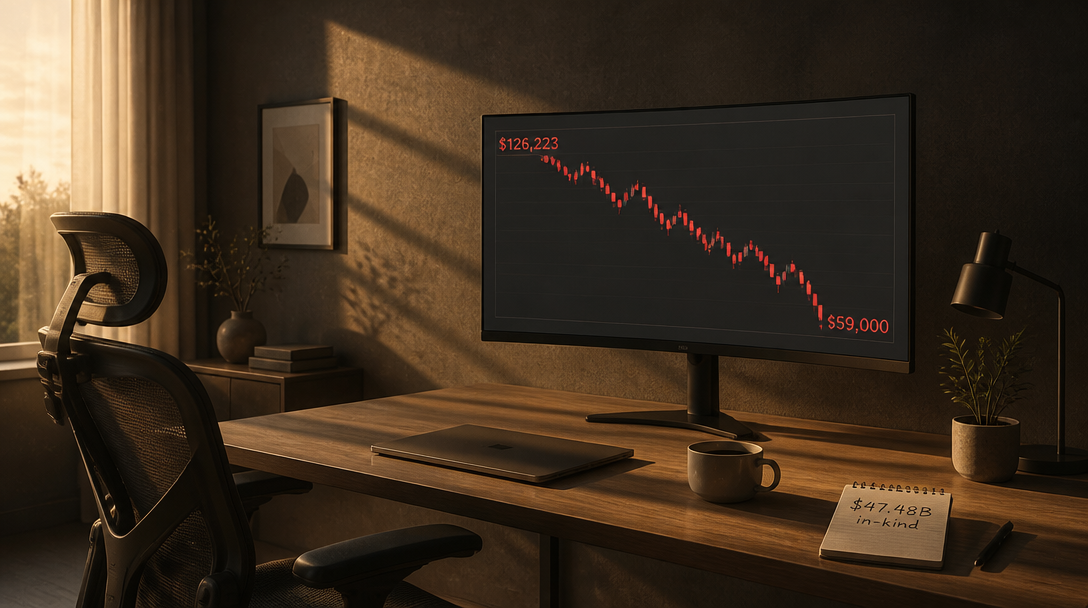
Bitcoin has fallen roughly 50% from its October 2025 peak of $126,223, but the decline is unfolding differently than prior bear markets. Unlike 2022, when cascading defaults across Terra, Three Arrows Capital, Celsius, Voyager, BlockFi, and FTX defined the downturn, the current sell-off is characterized by institutional redemptions and corporate treasury liquidations rather than intermediary collapses.
BlackRock’s IBIT spot ETF held $47.48 billion in net assets as of August 4, 2026, maintaining a 0.03% median bid-ask spread throughout the decline. The fund’s operational stability reflects structural improvements to the ETF market since July 2025, when the SEC approved in-kind redemptions. That mechanism allows investors to withdraw Bitcoin directly from trusts without forcing market sales that would amplify losses.
Institutional demand, however, has deteriorated. Strategy, a public treasury company, sold 1,638 BTC for $104.73 million on August 3, according to an SEC filing dated that day. The company held 842,138 BTC on August 2. Corporate treasury sales and ETF outflows have drained the bid side of the market. Across three weeks in early June, ETF outflows reached $4.21 billion. Through June 30, net ETF outflows totaled $3.3 billion.
The decline has compressed realized capitalization. Glassnode found that realized capitalization fell 1.45% over 90 days to $1.07 trillion by June 17, 2026, indicating that holders were realizing losses. By July 8, long-term holders were realizing $280 million in losses per day on a 30-day average. Spot volume fell to its lowest level since 2019 in late July.
Galaxy Research measured a 51% drawdown by June 9, 2026, roughly eight months into the decline. That pace differs from prior cycles. The 2018 bear market erased about 84% of Bitcoin’s value over 12 months. The 2021-2022 bear market cut Bitcoin by roughly 77% over 12 months. The current decline has reached 50% in eight months, with Bitcoin trading below $59,000 on July 1 before recovering to roughly $64,000 in early August.
Citi reduced its 12-month ETF flow assumption from $10 billion to zero, according to data cited Average ETF holder cost basis stood near $83,000, meaning most institutional buyers entered above current prices. Stablecoin supply rose from $308 billion in Q1 to $318 billion, while the 30-day stablecoin rate fell near -2% by June 18, indicating weak demand for leverage.
The absence of a system-defining intermediary failure through August 5, 2026, distinguishes this downturn from 2022. Bitcoin’s 2025 historical volatility was roughly 42%, approximately half the 2021 reading, reflecting lower leverage and reduced speculative positioning entering the decline. The distributed nature of the sell-off has allowed prices to adjust without triggering cascading defaults in the financial system.