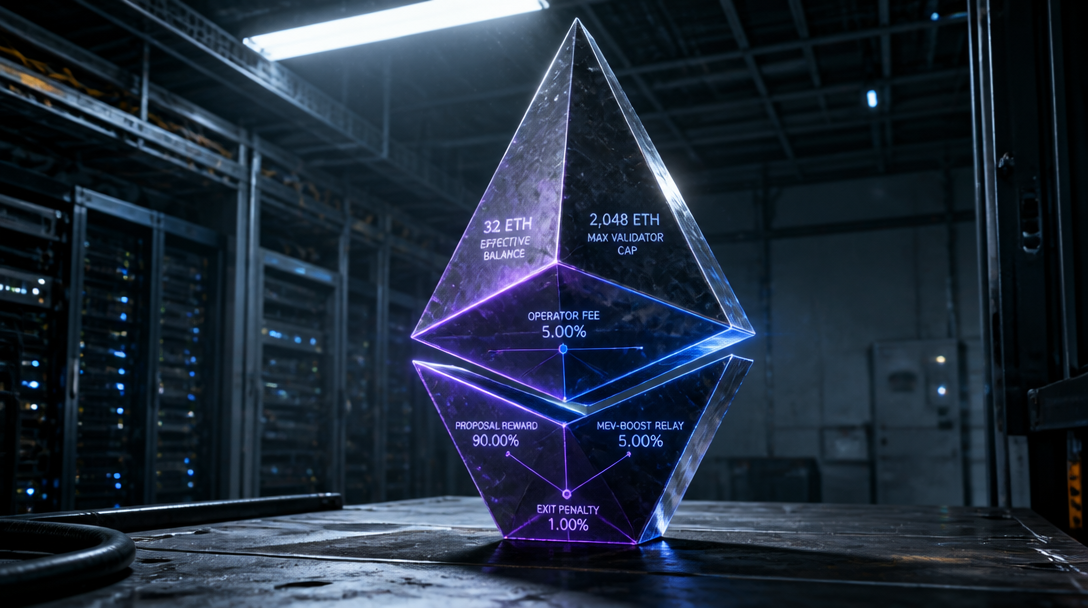
Lido is advancing Community Staking Module 0x02, a proposed validator framework requiring a 32 ETH entry bond for operators running compounding validators with up to 2,048 ETH effective stake. The module represents a departure from Lido’s existing default route, which requires only 2.4 ETH as a first bond.
The bond functions as an operator security deposit held as stETH to cover losses and charges. Posting the 32 ETH bond does not guarantee stake allocation. The protocol supplies validator stake separately, and allocation remains subject to module cap constraints and queue mechanics.
Module Design and Economics
Compounding validators under 0x02 can reach a maximum effective balance of 2,048 ETH while retaining 32 ETH as minimum activation balance, enabled by EIP-7251, an Ethereum protocol upgrade. Operators posting an additional key must post a 30 ETH bond, compared to 1.3 ETH under the existing default route.
The module imposes performance requirements: a 28-day performance frame with a 3% leeway threshold. Operators ejected for bad performance at full 2,048 ETH balance face a 16.512 ETH penalty. Exit delays at full balance incur a 6.4 ETH charge. Operator fees capture 2% of staking rewards; the protocol treasury receives 8%.
Lido modeled fee-parity thresholds for the new bond structure. Under equal conditions, the first key reaches fee parity at 747 ETH. When spreading the 32 ETH bond across existing default keys, fee parity occurs at 1,330 ETH. At maximum balance, the first key bond represents 1.5625% of delegated stake; subsequent keys represent 1.465%.
Governance Timeline and Testnet Status
Lido approved the launch proposal on July 20. The module moved to Hoodi testnet on September 1. An October 1 deployment plan outlined the path forward, though the exact announcement date was not specified.
Mainnet activation is expected in Q4 2026, contingent on Staking Router parameter votes. The module will operate under a 2% cap relative to total Lido stake, constraining allocation but not guaranteeing any operator a full validator slot.
The module remains permissionless, in contrast to verified profiles such as ICS and IDVTC, which carry lower bond requirements but require operator eligibility. Top-ups serve the queue head in multiples of 2 ETH, with a queue size limit of 16. A partly filled key remains at queue head until completion.
Fee-Parity Modeling and Incentive Structure
The 32 ETH bond structure introduces higher upfront capital requirements but enables larger validator stakes. The fee-parity thresholds reflect the trade-off: operators require sufficient delegated stake to offset the larger bond before rewards exceed costs under the new module versus the existing route.
At 1.3 ETH, the existing default route first bond represents a lower barrier to entry. The proposed 32 ETH bond targets operators with greater capital and risk tolerance, while the permissionless profile removes eligibility gatekeeping present in verified alternatives.