Committee Approves Taxable-Event Rule for MiCA E-Money Conversions
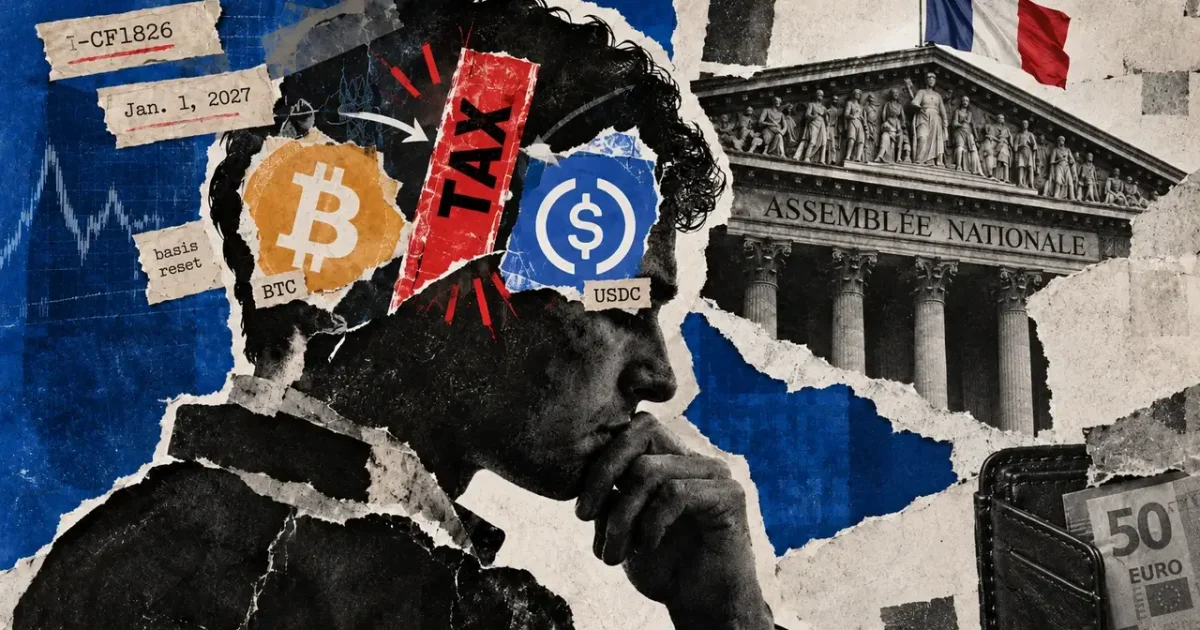
France’s National Assembly Finance Committee adopted amendment I-CF1826 on October 7, establishing that crypto-to-crypto swaps into MiCA e-money tokens like USDC will trigger taxable events before any cash withdrawal, effective January 1, 2027. The provision closes what amendment sponsors characterized as a “deferral on fiat-backed stablecoin conversions as a legislative loophole” under current French tax authority guidance.
Under existing rules, crypto-to-crypto exchanges without cash balancing payments receive tax deferral. Converting into fiat or using crypto to obtain goods or services can already be taxable under France’s private-disposal regime. The amendment redefines swaps into e-money tokens as taxable disposals, requiring recognition of gains or losses at the moment of conversion, not upon eventual cash withdrawal.
Basis Calculation Methods for Pre-2027 Holdings
The amendment offers two basis calculation routes for assets held before the January 1, 2027 effective date. Taxpayers may use evidenced actual acquisition costs or calculate basis through portfolio allocation under old rules as of December 31, 2026. The allocation option is irrevocable once the first tax return reporting a taxable disposal after January 1, 2027 is filed.
Under the actual-cost method, a hypothetical trader holding 1 Bitcoin acquired for €20,000 and 1 Ether acquired for €40,000 would recognize a €40,000 gain when swapping the Bitcoin into USDC valued at €60,000. The Ether would show €0 gain if its market value remained €40,000 at conversion.
Under the allocation method, the same portfolio valued at €100,000 total (€60,000 acquisition cost) would allocate basis proportionally. Bitcoin, representing 60% of portfolio value, receives €36,000 basis; Ether receives €24,000. The Bitcoin-to-USDC swap would then show a €24,000 gain, while the Ether conversion would show a €16,000 gain.
Gain Recognition and Loss-Offset Restrictions
Taxable exchanges give received crypto-assets a basis equal to the consideration value used to calculate the gain. Deferred exchanges carry surrendered assets’ basis into received assets. A trader holding 1 Bitcoin acquired for €30,000 who receives €20,000 in USDC would recognize a €10,000 loss. If that same trader later swaps €20,000 in USDC for another asset valued at €30,000, the €10,000 gain would be recognized on the second transaction.
Existing French tax rules prevent net crypto losses from offsetting later-year gains or gains on other assets, a restriction the amendment does not alter. The National Assembly plenary is scheduled to discuss the 2027 budget dossier on October 13, where the amendment’s status may advance further.
Circle, issuer of USDC, identifies the token as an e-money token under MiCA in its European white paper. MiCA’s definition describes a crypto-asset that seeks to maintain stable value by reference to one official currency.