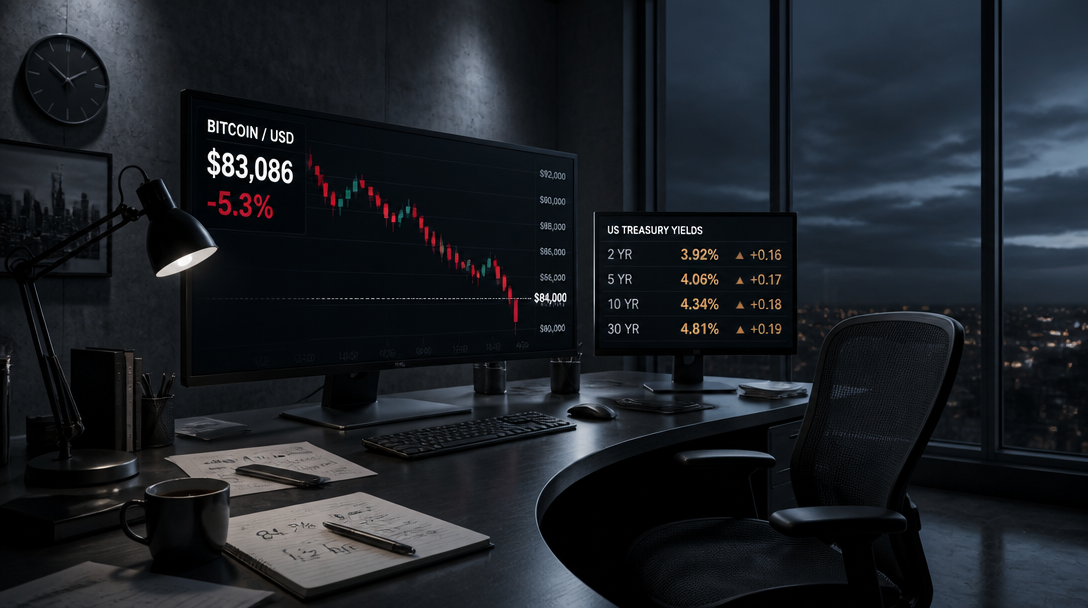
Bitcoin traded below $84,000 on October 7 while ten-year Treasury yields approached 5.3%, marking the highest nominal and real yield readings in a daily data series stretching back to January 2017, according to analysis by CryptoSlate.
The price level came as the asset has gained 84.2% since January 10, 2024, the day before US spot Bitcoin ETF trading began. Over the same period, ten-year nominal yields rose 127 basis points and real yields climbed 113 basis points, creating a competing return profile for investors weighing speculative crypto exposure against interest-bearing alternatives.
Weak Daily Correlation Despite Rising Yields
CryptoSlate examined 2,435 matched daily changes from January 2017 through October 5, 2026 to assess whether Bitcoin returns move inversely with Treasury yields. The analysis found minimal linear relationships. The Pearson correlation between ten-year nominal yield changes and Bitcoin daily returns since January 2017 stood at negative 0.004. For real yields, the correlation was negative 0.047.
In the post-ETF period starting January 11, 2024, daily correlations remained weak. Nominal yield correlations shifted slightly positive to 0.054, while real yield correlations reached 0.042 across 682 matched daily observations.
“Weak daily correlations and different monthly results limit any simple bearish price signal from higher Treasury yields,” CryptoSlate stated in its analysis.
The dollar index showed similarly weak daily relationships. Bitcoin and ICE DXY returns carried a negative 0.098 correlation since January 2017 and negative 0.089 post-ETF.
Monthly Data Tells a Different Story
Monthly sampling produced divergent results. From February 2017 through September 2026, nominal yield changes and Bitcoin monthly returns showed a negative 0.081 correlation. Real yields carried a stronger negative 0.228 correlation over the same 116 full months analyzed.
The post-ETF sample of 32 full months reversed direction. Nominal yield correlations turned positive at 0.207, and real yield correlations reached positive 0.126. Dollar-index correlations stayed near zero at 0.002.
The shift from negative to positive monthly correlations in the post-ETF period reflects the smaller sample size and does not establish a durable structural change in Bitcoin’s yield sensitivity, according to the analysis framework.
Context on Macro Relationships
Higher Treasury yields can increase the return investors demand to justify exposure to volatile, non-yielding assets like Bitcoin. S&P Global’s prior research found that crypto’s relationship with interest rates has varied over time and did not establish clear monetary-policy causality, providing context for why simple yield-versus-Bitcoin models may not hold consistently.
On October 6, 2026, the ten-year nominal par yield stood at 5.27% and the real par yield at 2.91%, representing the peak levels in the daily series examined. Bitcoin’s price at 14:25 UTC on October 7 was $83,086.