The U.S. Securities and Exchange Commission approved a proposed rule on October 1, 2025, that would permit investment advisers to hold client crypto assets in self-custody when no qualified custodian is available, subject to safeguards including independent control reports and dual authorization.
The proposal applies to covered crypto assets that are funds or securities for ordinary advisory clients. For regulated-fund accounts, the scope is limited to securities or similar investments. Advisers must establish a written reasonable basis, after due inquiry, that no qualified custodian would maintain each asset before taking custody and at least quarterly thereafter.
SEC Commissioner Hester Peirce issued a statement on September 30, 2025, describing conditional staff no-action relief and distinguishing adviser “self-custody” from investors holding their own assets. The distinction underscores the regulatory framework: advisers retaining client assets must meet standards that individual holders do not.
Cost Structure and Firm-Size Implications
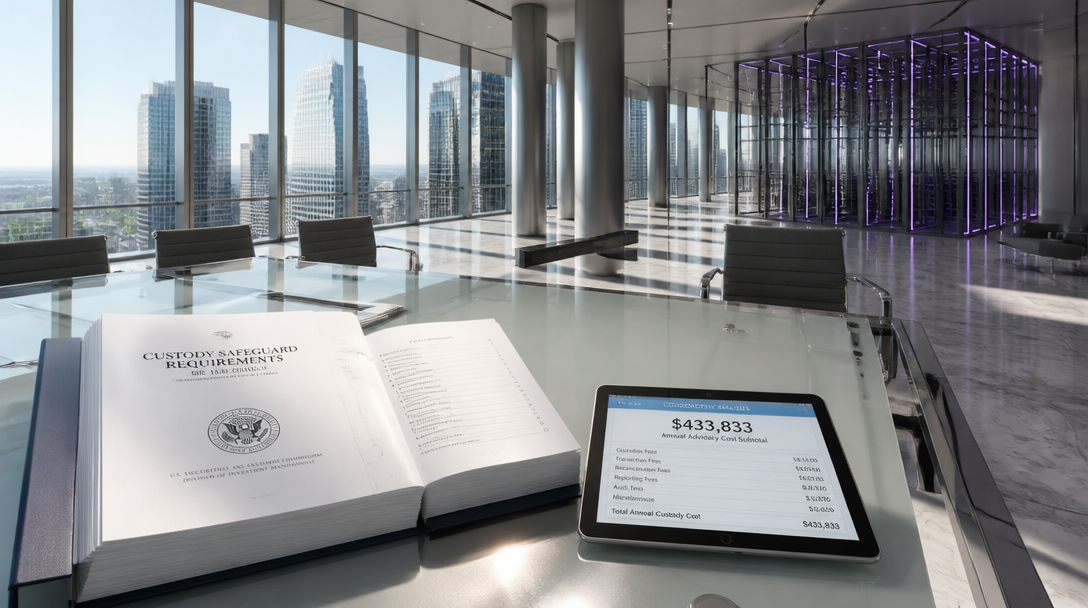
The SEC modeled annual adviser costs for the self-custody option at $433,833, comprising $376,000 for an average independent internal control report and $57,833 in recurring internal compliance work annually. Initial internal compliance costs total $173,499, based on a $578.33 hourly rate and 300 initial hours. Recurring work assumes 100 annual hours at the same rate.
The SEC estimates that 823 advisers, or 5% of the 16,442 registered advisers, would use the self-custody option. The cost structure creates a differential impact by firm size: larger advisers can spread compliance expenses across more client assets and existing infrastructure, while smaller advisers face the same fixed costs with less volume to amortize.
The SEC acknowledged that the $433,833 estimate excludes potentially significant technology, software, hardware, and associated systems costs, leaving total implementation costs uncertain. The regulator also cautioned that accountant pricing for crypto control assessment expertise could work either way: demand for such services could make them harder to obtain, particularly for smaller advisers with less bargaining power.
Safeguards and Operational Requirements
Advisers choosing self-custody must demonstrate asset-specific expertise and maintain key management systems. Authorization of crypto transfers requires approval by two or more designated people. Each client’s assets must be segregated.
The first independent control report is due within six months of taking self-custody, then at least once each calendar year. Advisers must provide quarterly client reporting, with electronic alternatives and exceptions available for qualifying audited pools and regulated funds.
Custodian costs cannot form the basis for choosing the fallback option. The relevant barrier is availability of an eligible custodian. Eligible custodians under the proposal include state trust companies, national banks, and state banks. Once a qualified custodian becomes available for an asset, the adviser must transfer it as soon as reasonably practicable.
The SEC emphasized that spending on compliance infrastructure does not establish safeguarding competence. A firm’s ability to absorb compliance costs is separate from whether its systems effectively protect clients.