Interest spread could collapse under rising funding costs
Aave Labs published a proposal on September 24 for a $50 million institutional lending facility where institutions pledge BTC or ETH as collateral for dollar loans. The structure relies on the Aave DAO borrowing stablecoins against its own crypto assets to fund the loans. A critical vulnerability emerged in the proposal: the interest spread between what borrowers pay and what the DAO pays to fund the loans could evaporate entirely, leaving Aave Labs unable to cover custody, operating, and credit costs even if every loan performs.
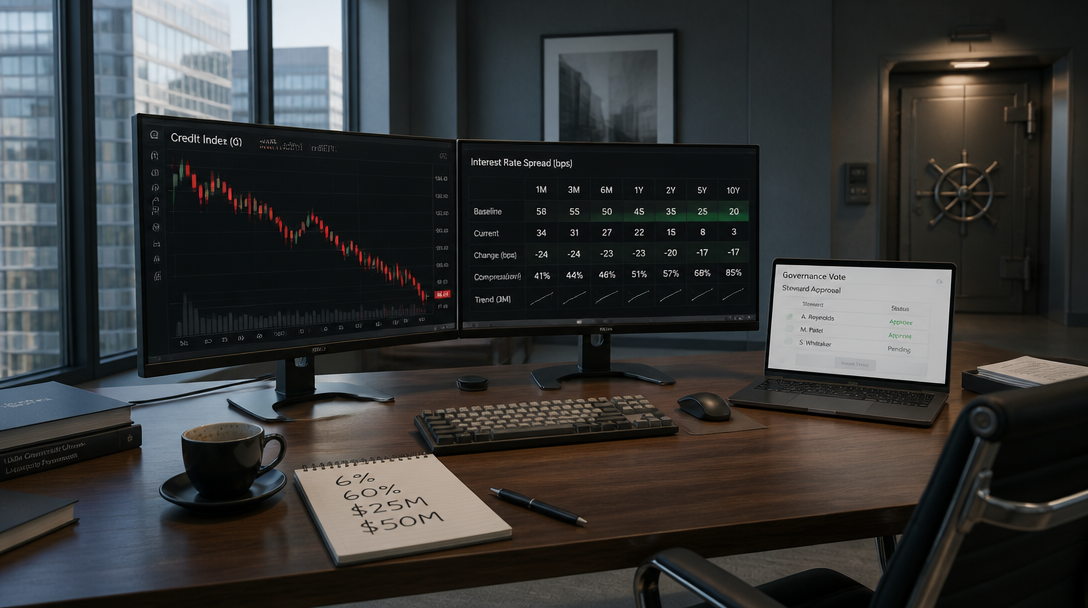
The facility would operate through two channels. A $25 million GHO issuance bucket would convert newly minted GHO into dollars for borrowers. A separate $25 million authorization would allow the DAO to borrow USDC or USDT directly on Aave V3. Institutions would pledge collateral with a qualified custodian under a Master Loan Agreement with an Aave Labs entity, with loan-to-value ratios typically ranging from 60% to 75%. Proposed borrower rates span 6% to 8% APR.
The math deteriorates quickly. TokenLogic, lead of the Aave Finance Committee and governance approver, stated that “the balance-sheet route would pay the prevailing V3 rate for borrowed USDC or USDT.” At a 4.5% funding cost, Aave Labs would retain a 1.5 to 3.5 percentage point spread. But if funding costs rise to 6%, the spread collapses to zero at the low end of the borrower rate. At 7% funding costs, the loan coupon falls below the cost of funds even with full repayment.
The problem compounds because institutional loan coupons are fixed by contract and remain locked during a 90-day notice period. Aave V3 rates, by contrast, adjust continuously as liquidity is borrowed or repaid. If the DAO borrows at a variable rate while charging borrowers a fixed rate, a spike in pool utilization during those 90 days could push funding costs above the contracted loan rate before Aave Labs can reset terms.
TokenLogic emphasized that “inventory is insufficient to support a loan of the proposed size and duration without liquidity management.” As of September 24, the Stability Module held $59.9 million in redemption inventory. The proposal indicated $300 million in institutional demand, suggesting the $50 million authorization would be heavily oversubscribed.
The GHO-funded route introduces additional complexity. TokenLogic stated that “matched sGHO inflows must last at least as long as borrower drawings.” The DAO would need to manage GHO peg effects while ensuring redemption liquidity remains available for the duration of each loan.
Aave Labs issued a clarification on September 30 but the core structural risk remains unresolved. Governance approval requires two-of-three votes from Aave Labs, TokenLogic, and LlamaRisk among GHO Stewards. The proposal does not disclose which assets the DAO would pledge as collateral or in what proportions, nor does it specify the precise allocation of losses between the Aave Labs entity and the DAO.