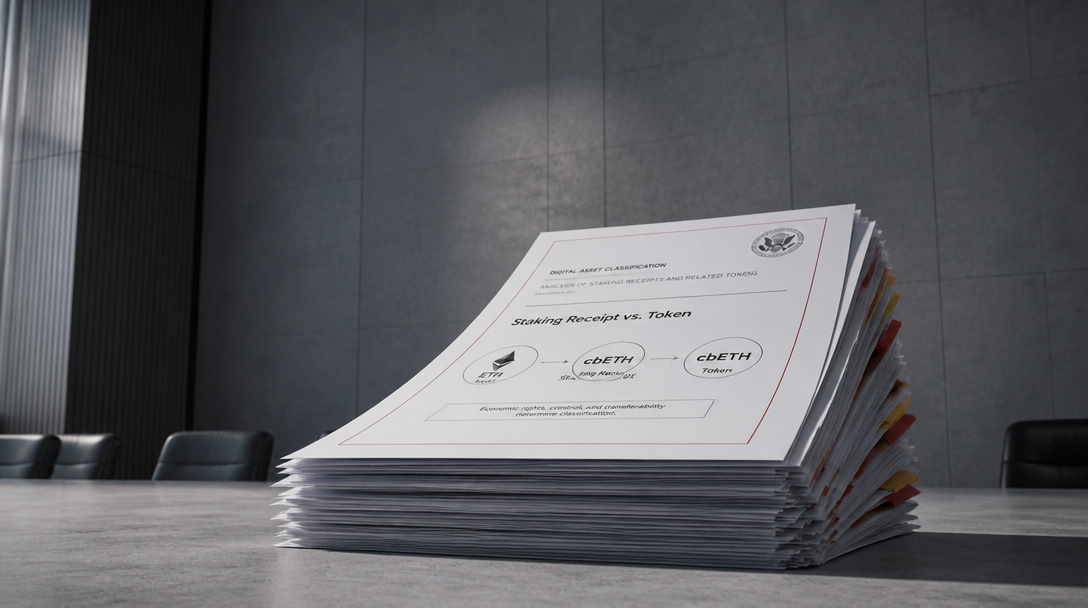
The SEC’s Division of Corporation Finance has drawn a regulatory line between two types of liquid-staking products, classifying one category as a “digital tool” and the other as a “digital commodity,” creating potential compliance uncertainty for holders of staked ETH tokens like Coinbase’s cbETH and Lido’s stETH.
The distinction emerged in an SEC staff FAQ published September 25, 2025, following an earlier statement in August 2025. The agency said a qualifying staking receipt may be a digital tool, while a protocol-issued token may be a digital commodity. The classification carries weight because it signals how the SEC may treat redemption rights and exit guarantees for millions of dollars in staked assets.
How Coinbase’s cbETH Works
Coinbase’s cbETH represents ETH staked through Coinbase’s custodial infrastructure. When holders stake ETH via Coinbase, they receive cbETH in return, which represents their staked ETH plus accrued rewards minus Coinbase’s fees and any slashing penalties. Coinbase holds the staked ETH on behalf of token holders; ownership does not transfer to Coinbase itself.
cbETH holders can sell the token on secondary markets, but the secondary-market price may diverge from the underlying ETH value. To redeem cbETH contractually, holders must maintain a Coinbase account in good standing, meet staking eligibility requirements, and complete an unwrapping step that returns staked ETH. This process is separate from Ethereum’s own unstaking mechanism, which adds another layer to the exit sequence.
Lido’s Protocol-Based Model
Lido’s stETH operates through protocol smart contracts rather than a custodial arrangement. Holders deposit ETH directly into the protocol and receive stETH in return. Redemption occurs either through Lido’s protocol withdrawal queue or through secondary-market sale.
Lido’s risk disclosure identifies queue delays, Ethereum validator exit constraints, slashing risks, and secondary-market liquidity constraints as potential obstacles to exiting the position. The protocol does not guarantee immediate redemption or a fixed exit price.
SEC’s Analytical Scope
The SEC’s August 2025 statement limited its analysis to transferable evidence of deposited assets and accrued rewards. The agency explicitly excluded from its analysis arrangements involving restaking, provider-controlled staking choices, guaranteed rewards, or additional token returns. The September 25 FAQ did not classify cbETH or stETH by name, leaving the specific regulatory status of these widely used tokens unresolved.
According to the SEC Division of Corporation Finance, a staking receipt that qualifies as a “digital tool” and a protocol-issued token classified as a “digital commodity” may face different regulatory treatment. The distinction suggests that custodial products like cbETH and protocol-native products like stETH could fall into separate regulatory categories, though the agency has not yet issued formal determinations for either token specifically.
Redemption and Exit Uncertainty
For cbETH holders, redemption requires navigating Coinbase’s account requirements, eligibility checks, and the unwrapping process before accessing the underlying staked ETH. For stETH holders, redemption may face queue delays and secondary-market liquidity constraints identified in Lido’s own disclosures.
The SEC’s split classification raises questions about whether redemption rights and exit guarantees will receive consistent regulatory oversight. Holders of either token face potential friction in converting their staking receipts or tokens back to unstaked ETH, with no SEC guidance yet specifying how each category’s redemption mechanics will be treated under securities or commodities law.