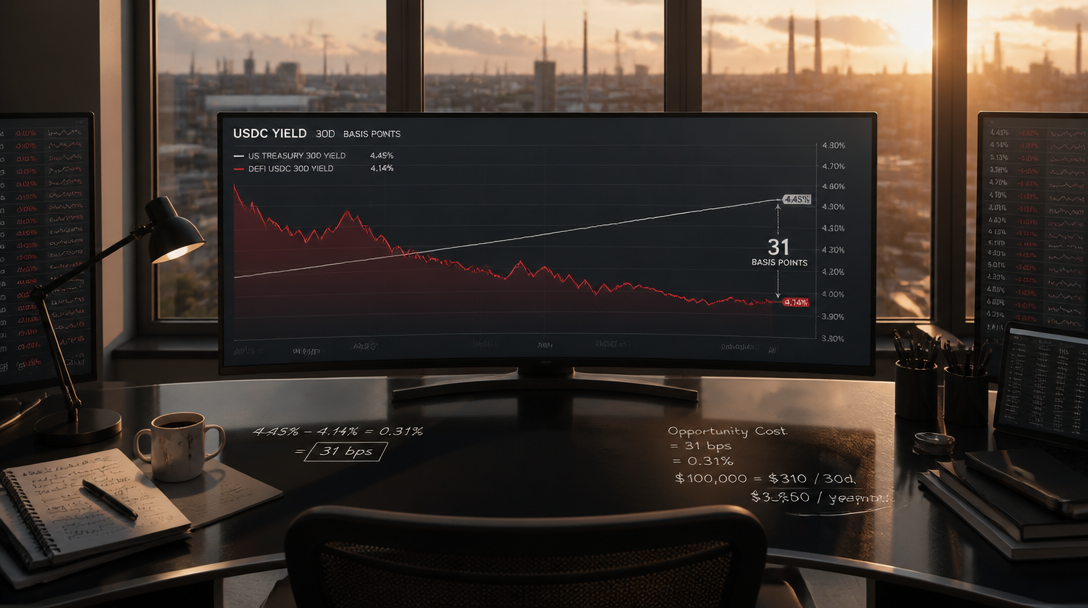
The Federal Reserve raised its target rate to 3.75% to 4.00% on September 16, lifting the one-year Treasury yield to 4.45% and widening a structural gap between traditional fixed-income returns and decentralized finance lending rates.
Coin Metrics found that throughout 2026, Aave USDC lenders earned 31 basis points less than the one-year Treasury on average. The shortfall persisted in 78% of measured intervals, suggesting that stablecoin investors choosing DeFi platforms over risk-free government debt face consistent opportunity costs even as Fed policy tightens.
A European Central Bank working paper published September 14 documented that monetary-policy transmission into DeFi stablecoin deposit rates is weak and unstable in the short term. Rates can move opposite to Fed policy before converging over longer horizons. Deleveraging in crypto markets often drives short-run divergence, the ECB found.
Higher Yields, Higher Volatility
Morpho, a higher-yield vault protocol, offered a 65 basis point median premium over Treasury yields, but exhibited 3.3x the volatility of Aave. That risk-adjusted trade-off mirrors the broader tension in DeFi: larger yields require accepting concentration risk and smart-contract exposure that Treasuries do not.
Anthony DeMartino, co-founder and CEO of Sentora, an institutional DeFi platform, challenged the Treasury benchmark itself. “Correlation between SOFR and CDOR has been very low, so a Fed hike should not be expected to pull onchain rates materially higher, and SOFR is the wrong anchor for pricing onchain exposure,” DeMartino said.
CDOR tracks overnight borrowing rates on USDC and USDT inside Aave V3. DeMartino argued that the premium over CDOR is where actual credit and smart-contract risk are priced. “The premium over CDOR is where smart contract, liquidity, and credit risk are compensated, but there is no standard rate that can be applied here,” he said.
Tokenized Equity Vaults and Withdrawal Risk
Kraken, the San Francisco-based exchange, advertises 2% net annualized yield for SPYx and QQQx vaults, tokenized equity products that borrow stablecoins against collateral and deploy proceeds into DeFi reward strategies. The NVDAx vault yields 1.8% net. A $10,000 position at 2% generates $200 annually after Kraken’s 25% performance fee.
Withdrawals from Kraken vaults take three days and potentially longer under stress, introducing liquidity friction absent in Treasury markets. Returns compound automatically, but investors cannot access capital on demand.
The yield gap persists even as the Fed has tightened policy. Whether DeFi rates will converge toward Treasury levels or remain structurally depressed depends on whether deleveraging cycles continue to dominate short-term dynamics, a question the ECB working paper left open.